Here's a hard fact most people learn the worst way: a lot of the drivers around you carry little or no insurance. When one of them causes a crash, the at-fault "coverage" that's supposed to pay for your injuries may barely exist — or not exist at all. That's not the end of your case, but it changes everything about how it has to be built, and it's exactly the scenario an unrepresented person handles wrong.
I'm Scott DeSalvo, and I've handled crash cases across the Chicago area for almost 30 years. Whether you were hit on Mannheim Road, on St. Charles, or near the Eisenhower in Bellwood, my job is to find every dollar of coverage that applies and make sure your own injuries get paid for. The first call is free.
If the driver who hit you had no insurance or too little to cover your injuries, your own policy may be what saves you. Uninsured and underinsured motorist coverage — which Illinois insurers are required to offer — lets you recover from your own carrier when the at-fault driver can't make you whole. Most people don't realize they carry it, and even those who do are often surprised how the claim works.
The catch is that your own insurer, in that situation, starts acting like the opponent — because now it's the one being asked to pay. I handle that claim the same way I'd handle a claim against the other driver, because in practical terms that's what it is.
Adrenaline hides damage. Right after the crash you may feel rattled but basically okay, so you tell the officer and the other driver you're fine — and a day or two later your neck won't turn or your back locks up. By then the insurer has your own words saying you weren't hurt, and they'll lean on them.
Neck, back, and head injuries commonly surface a day or two after impact. Get examined promptly even if you feel alright, and let your medical records, not a remark at the scene, define your injuries.
The adjuster who calls sounding friendly has one goal: to pay you less. They'll push for an early recorded statement, ask questions built to trap you, and float a quick check before your injuries are clear. You are not required to give the at-fault driver's insurer a recorded statement, and you usually shouldn't. Tell them your lawyer will be in touch, and let me take it from there.
This trips up almost everyone: the at-fault driver's insurer won't pay your medical bills as you go — it pays once, at the end, if it pays fairly, leaving the bills to you in between. Your own Medical Payments coverage, if you carry it, pays regardless of fault, and your health insurance can bridge the rest. Between MedPay, health coverage, and uninsured-motorist benefits, there are often more sources of recovery than people expect, and I dig through every one.
Bottom line: the damage to your car is the least important number in the case — don't let anyone settle it as if it's the whole story.
Call me and tell me what happened. I'll tell you honestly whether you have a case, find every policy that might apply, deal with the adjusters, and charge you nothing unless I win. You pay nothing out of pocket.
I'm reachable any time, day or night. Call 312-500-4500.
A car crash may not be your only claim. For the complete picture of how I help injured people here, start with my Bellwood Personal Injury Attorney page.
"Scott is absolutely fantastic. He will always go the extra mile for his clients. They always take the time to return phone calls at all hours and I highly recommend him to all my friends."
-Melissa Brooks
"Great people and Scott's a great lawyer. They helped me make the wisest decision for my case, and that's important in serious legal matters. I trust him completely. He is the one to call."
-Tony Skvarenina
"Beyond satisfied with the services I received from this law firm. Definitely recommend! They got me fully paid and all the doctor bills, too. If you want the best, this is the law firm for your injury case!"
-Cynthia Rodriguez
"Scott represented me and I was really pleased with everything, my car accident paid a lot and quick. If you want a good Lawyer who is responsive, and straight with you, I highly recommend him."
-Greg Garcia
Not necessarily. If you carry uninsured or underinsured motorist coverage — which Illinois insurers must offer — you may recover from your own policy when the at-fault driver can't cover your injuries. Many people don't realize they have it. I'll review your coverage closely and pursue every source available to you.
Generally two years from the date of the crash under Illinois law. But evidence disappears long before then — camera footage is overwritten, vehicles are repaired, and witnesses forget — and if a government vehicle was involved, the deadline can be much shorter. Calling early protects both the proof and your claim.
No. You're not required to give the at-fault driver's insurer a recorded statement, and it usually helps them more than you. Their adjusters ask questions designed to lock in answers they can later use to cut your claim. Decline politely, tell them your lawyer will follow up, and let me handle those calls.
Possibly. Insurers argue that minor damage rules out injury, but that's not how the body works — real neck and back injuries happen at low speeds. Your medical evidence decides the claim, not the condition of your bumper. Don't let an adjuster talk you out of a genuine injury.
Nothing unless we win. I work on contingency — my fee, 33 1/3% (or 40% if the case goes into litigation), comes only from what I recover for you, and I advance the costs. If we don't win, you owe nothing.
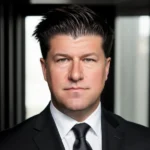
Scott DeSalvo founded DeSalvo Law to help injured people throughout Chicago and surrounding suburbs. Licensed to practice law in Illinois since 1998, IARDC #6244452, Scott has represented over 3,000 clients in personal injury, workers compensation, and accident cases.
No Fee Unless You Win | Free Consultation | 24/7 Availability Call or Text: (312) 500-4500
>>Read More
Main Office:
1000 Jorie Blvd Ste 204
Oak Brook, IL 60523
New Cases: 312-500-4500
Office: 312-895-0545
Fax: 866-629-1817
service@desalvolaw.com
Chicago and Other Suburban Offices
By Appointment Only